A Guide to Construction Equipment Leasing for Small Businesses
7 min read
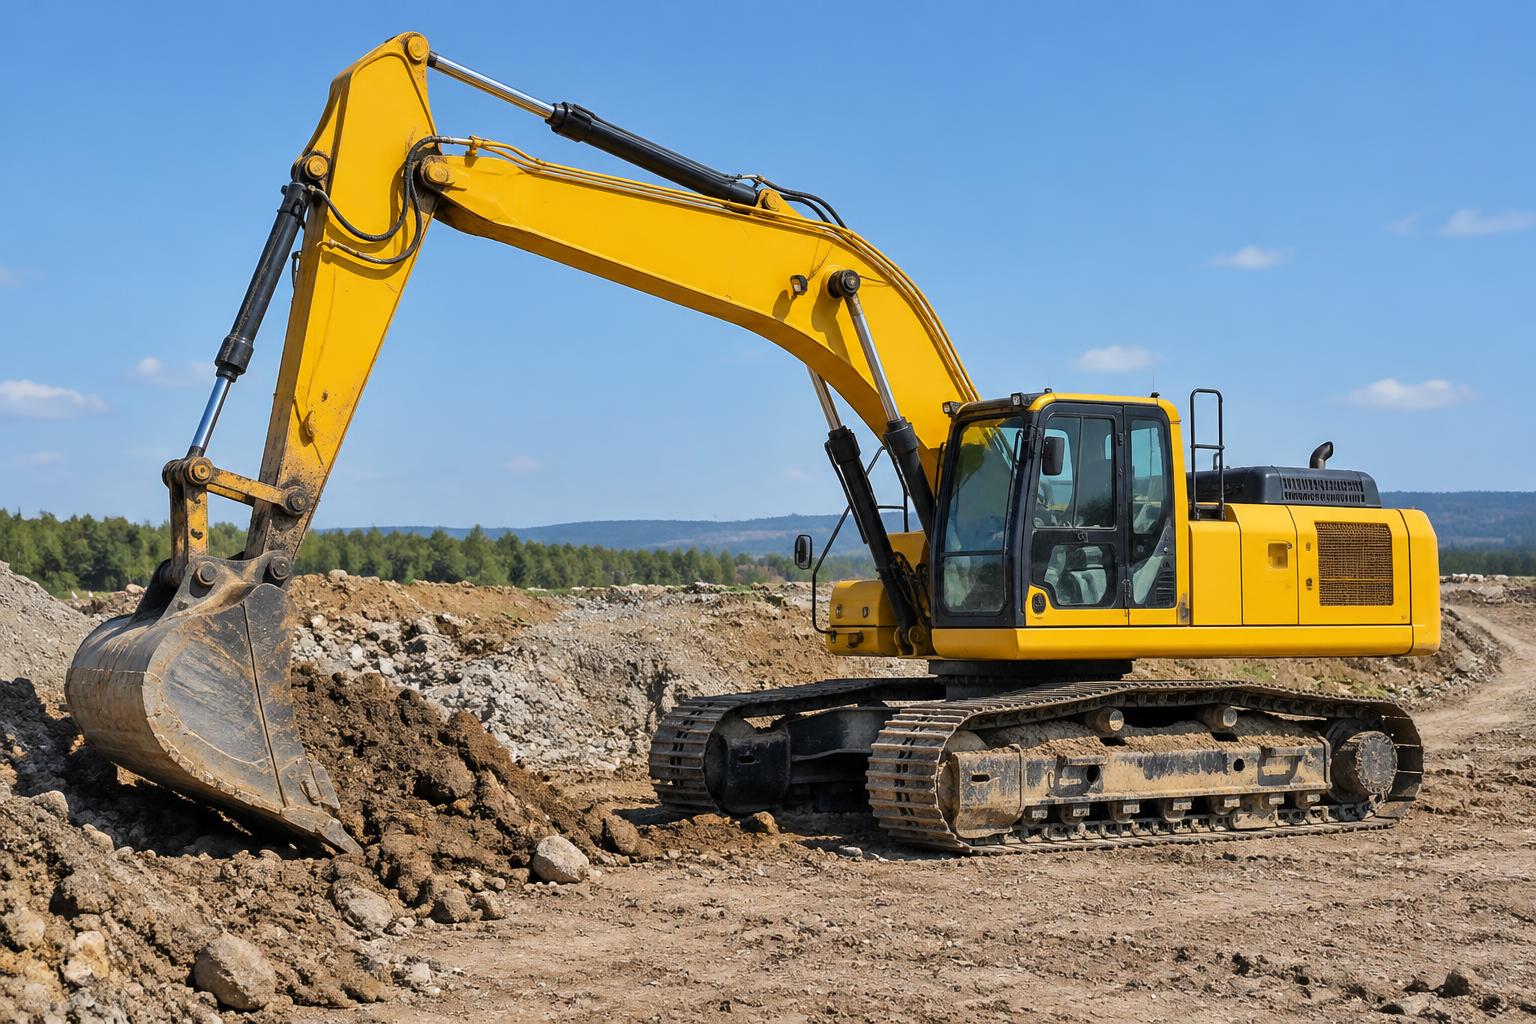
For small business owners in the construction sector, the ability to access heavy machinery without depleting cash reserves is a fundamental driver of growth. Equipment leasing offers a flexible path to acquiring excavators, loaders, and specialized tools while maintaining the liquidity needed for payroll and materials. As an industry, equipment finance represents a significant portion of the U.S. This guide explores how your business can leverage leasing structures to stay competitive in an evolving landscape.
Understanding Construction Equipment Leasing
Construction equipment leasing is a contractual agreement where a business pays for the use of machinery over a set period rather than purchasing it outright. This model is particularly beneficial for high-value assets that may have long lifespans but require significant upfront investment. By spreading the cost over several years, businesses can align their expenses with the revenue generated by the equipment.
Leasing typically falls into two main categories: operating leases and capital leases. An operating lease functions similarly to a long-term rental, often providing lower monthly payments and the ability to return the equipment at the end of the term. A capital lease, conversely, is structured more like a loan where the lessee intends to take ownership of the asset at the end of the term, often for a nominal fee like one dollar or a fixed percentage of the original cost.
The Strategic Benefits of Leasing Over Buying
One of the primary advantages of leasing is the preservation of working capital. In the construction industry, project delays and fluctuating material costs are common; having cash on hand provides a vital safety net. Leasing allows you to acquire the latest technology and Tier 4 emissions-compliant engines without a massive down payment, which typically ranges from 0% to 20% depending on the applicant's credit profile and time in business.
Additionally, leasing provides a hedge against obsolescence. As construction technology advances—incorporating GPS grading systems and telematics—leasing allows firms to upgrade their fleet every few years. This ensures that your crews are working with the most efficient, fuel-saving, and safe machinery available, which can be a deciding factor when bidding on municipal or large-scale private contracts.
Tax Implications and Section 179
Financing construction equipment can offer significant tax advantages under U.S. tax code. Many businesses utilize Section 179, which may allow for the immediate expensing of the full purchase price of qualifying equipment in the year it is put into service. This can result in substantial tax savings, effectively reducing the net cost of the equipment acquisition.
It is important to note that the eligibility of a lease for these deductions depends on the specific structure of the agreement and the current tax laws. We strongly advise that you consult with a qualified tax professional or CPA to determine how leasing will impact your business’s specific tax liability and to ensure compliance with IRS regulations.
- Potential for 100% write-off of equipment costs under Section 179.
- Ability to deduct monthly lease payments as an operating expense.
- Consultation with a tax professional is required to confirm eligibility.
Standard Terms and Approval Requirements
Lease terms for construction equipment are highly variable and depend on the age of the asset and the financial health of the business. Typically, terms range from 24 to 72 months. While new equipment often qualifies for longer durations and lower rates, used equipment—often defined as machinery up to 10 or 15 years old—can also be financed, though it may require a larger down payment or shorter term.
Lenders generally look at a combination of credit scores, years in business, and bank statements to determine eligibility. A business with two or more years of operating history and a solid credit profile will often find the most competitive options. However, there are programs designed for newer businesses that may require additional collateral or a personal guarantee from the business owners.
Steps to Secure Equipment Financing
The process begins with identifying the specific piece of equipment needed and obtaining a quote from a dealer or private seller. Once you have a clear understanding of the cost, the next step is to submit an application through an education and referral platform like Equipment Finance Academy. This allows your information to be reviewed by partner lenders who specialize in construction assets.
Once a preliminary approval is issued, you will receive a document detailing the monthly payment, the term length, and any end-of-lease options. It is crucial to review these documents carefully to understand your obligations regarding insurance, maintenance, and taxes. After signing and the verification of the equipment, the lender typically pays the vendor directly, and the equipment is delivered to your job site.
- Identify equipment and obtain a formal quote or invoice.
- Submit financial documentation including recent bank statements.
- Review and sign the lease agreement after choosing the best term.
- Coordinate delivery once the vendor has been funded.
Frequently asked questions
Can I lease used construction equipment?
Yes, used equipment is frequently leased. Most lenders will finance used machinery provided it is in good working condition, though the age of the equipment may influence the maximum length of the lease term.
What happens at the end of a construction equipment lease?
Depending on your lease type, you may have the option to purchase the equipment for a set price (such as $1 or 10% of the fair market value), renew the lease, or return the equipment to the lessor.
How long does the approval process take?
The approval process can be quite fast, often ranging from a few hours to a couple of business days, depending on the complexity of the transaction and the completeness of the application.
Ready to see your options?
Check financing options with a quick pre-qualification. Subject to lender approval.
Apply Now